An estimate is supposed to be a forecast. A specialist looks at the car, finds comparable sales and prints two figures in the catalogue. A specialist at Christie's told the researchers Alan Beggs and Kathryn Graddy what the aim is: that the sale price lands somewhere in the middle of the two.
An auction house also has good reason to be honest about it. According to Paul Milgrom and Robert Weber, writing in 1982, an auctioneer does better over time by telling bidders everything it knows. People who are surer of the value bid less cautiously. And a house whose figures keep missing eventually stops being believed.
The trouble is that an estimate has two readers, and the first reads it before any catalogue exists. A seller rings a few houses and asks what the car might fetch. A house earns only if the car comes to it. Naming a high figure costs nothing, because an estimate is not a bid and binds nobody. At that moment the number is an advertisement aimed at one person.
What the research says, and what about
In 2005 Jianping Mei and Michael Moses tested this in the Journal of Finance against thirty years of auction data. Estimates for expensive paintings ran consistently high. People who bought at a high estimate went on to earn worse returns, and the error stuck to the individual painting. The authors give two causes: the auction house's own interests and investors who believe the estimate too readily.
In 2009 Beggs and Graddy looked in the American Economic Review at where such a figure comes from. They used Impressionist and modern art sold in London and New York between 1980 and 1990, and found what psychologists call anchoring. If a painting last sold 10% above its predicted value, the new price came in 6.2% to 8.5% higher. The low estimate behaved in much the same way. The painting had not changed, but the old figure was still there.
Their account of the trade adds something else. Estimates are often set in negotiation with the seller. There is also an unwritten rule: the low estimate sits at or above the secret reserve. A seller with a high reserve therefore drags the low estimate upward. So the figure is partly the result of a negotiation, and that never appears in the catalogue.
All of this concerns paintings. We know of no comparable study on cars, and cars are easier to compare: there are thousands of 911s to look at. That ought to make estimates tighter, which is why one week of car auctions is worth a look.
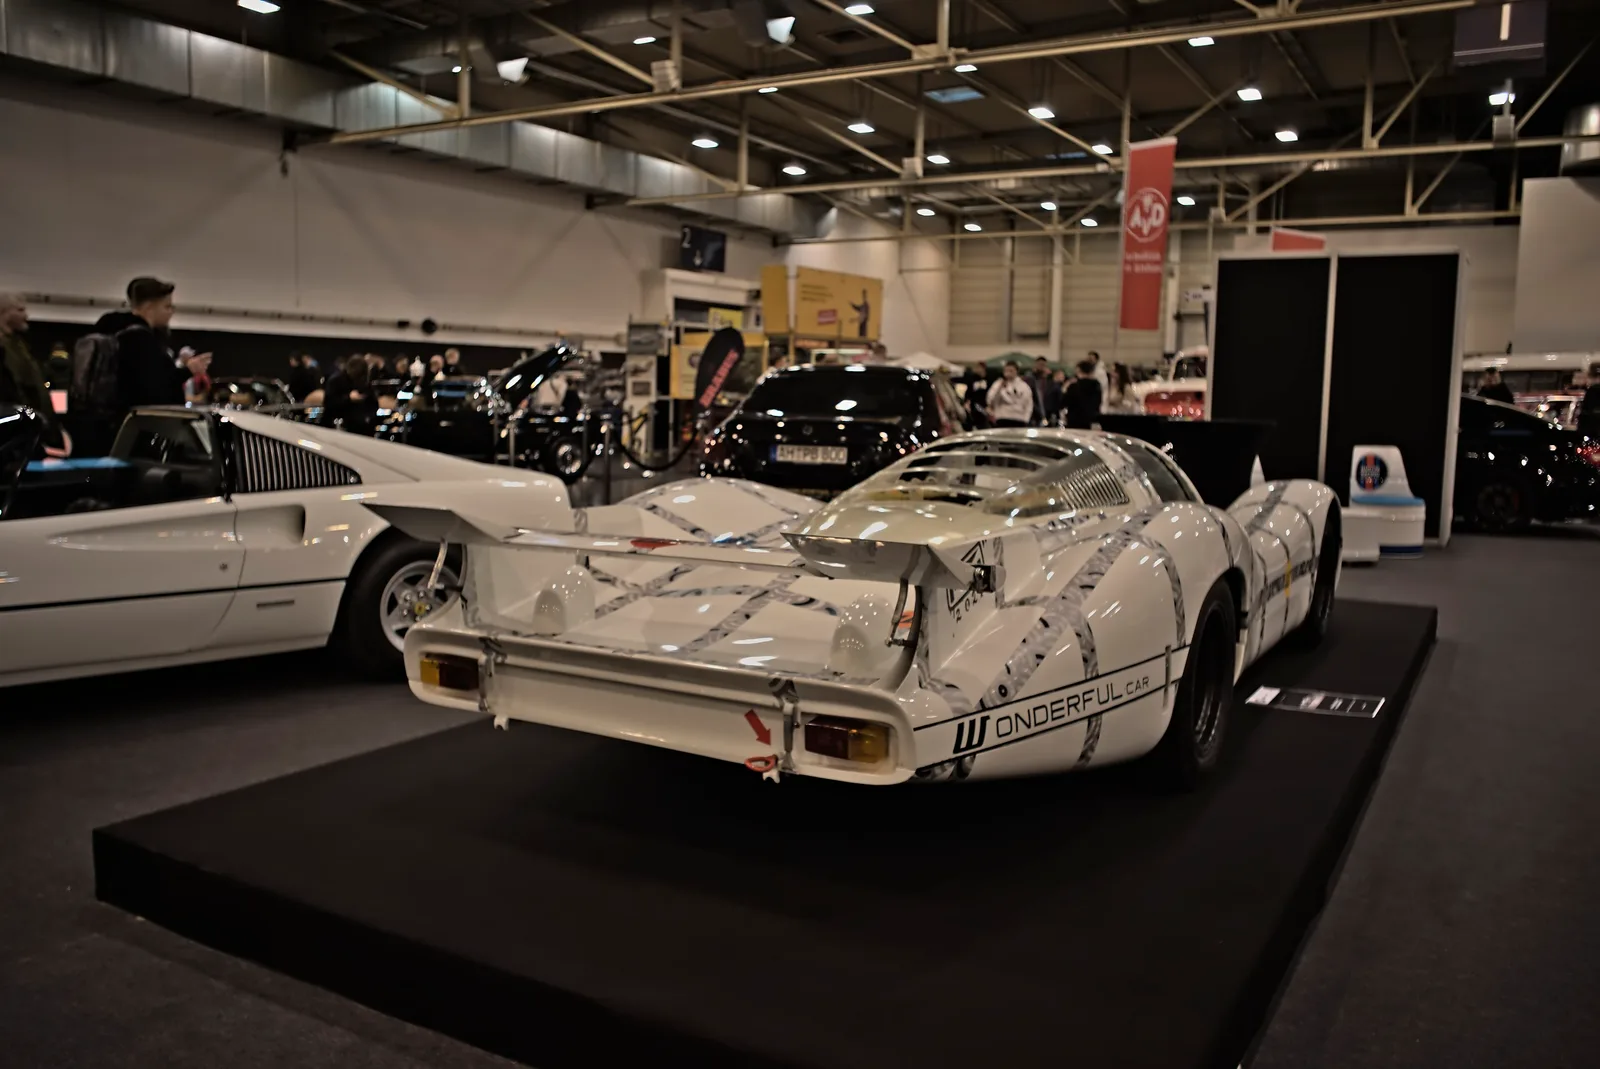
A Porsche 907 Langheck at the Essen Motor Show in 2022. The same type as the car below, not the same car.
One week in Monterey
West Coast Shipping, an American car transporter, set results against estimates after Monterey Car Week in August 2026. It is not an academic source and the firm earns money moving such cars, but it shows its method. Of 467 cars sold at Gooding Christie's, Broad Arrow, Bonhams and Mecum, 241 went below the low estimate. That is 52%. Among those 241 the median was 19% under. Even that is generous. The prices include buyer's premium and the estimates do not. Cars that failed to sell are not counted.
Take the 1968 Porsche 907 Langheck, chassis 907-005. Gooding Christie's catalogued it at $4.5 million to $5.5 million. According to that tally it sold for $3,305,000. Take off roughly 10% of premium and the hammer fell at about $3 million, a third below the low estimate. Consider what that says about the reserve, which should sit at or below the low estimate. Here it was at least $1.5 million below, or it was cut on the day. The public figure and the one that mattered to the seller were a long way apart.
The same week, a few kilometres away, it went the other way. RM Sotheby's estimated a Ferrari F40 at $4 million to $5 million, and by the same tally it made $8.37 million. Of the 11 Ferraris sold in that selection, none finished below estimate. A low estimate is an advertisement as well, one that draws bidders who think they still have a chance. It may also simply be out of date. A catalogue is made well before the sale, and the market moves. From outside you cannot tell which.
Why does this not correct itself, as Milgrom and Weber would expect? Because the memory sits on the wrong side. Bidders return every year and learn to read the figures. The seller may sell such a car once in a lifetime, and hears the high number on the day they choose a house. By the time the result is in, the house has already had the car. An estimate that is too high costs it, at most, one unsold lot.
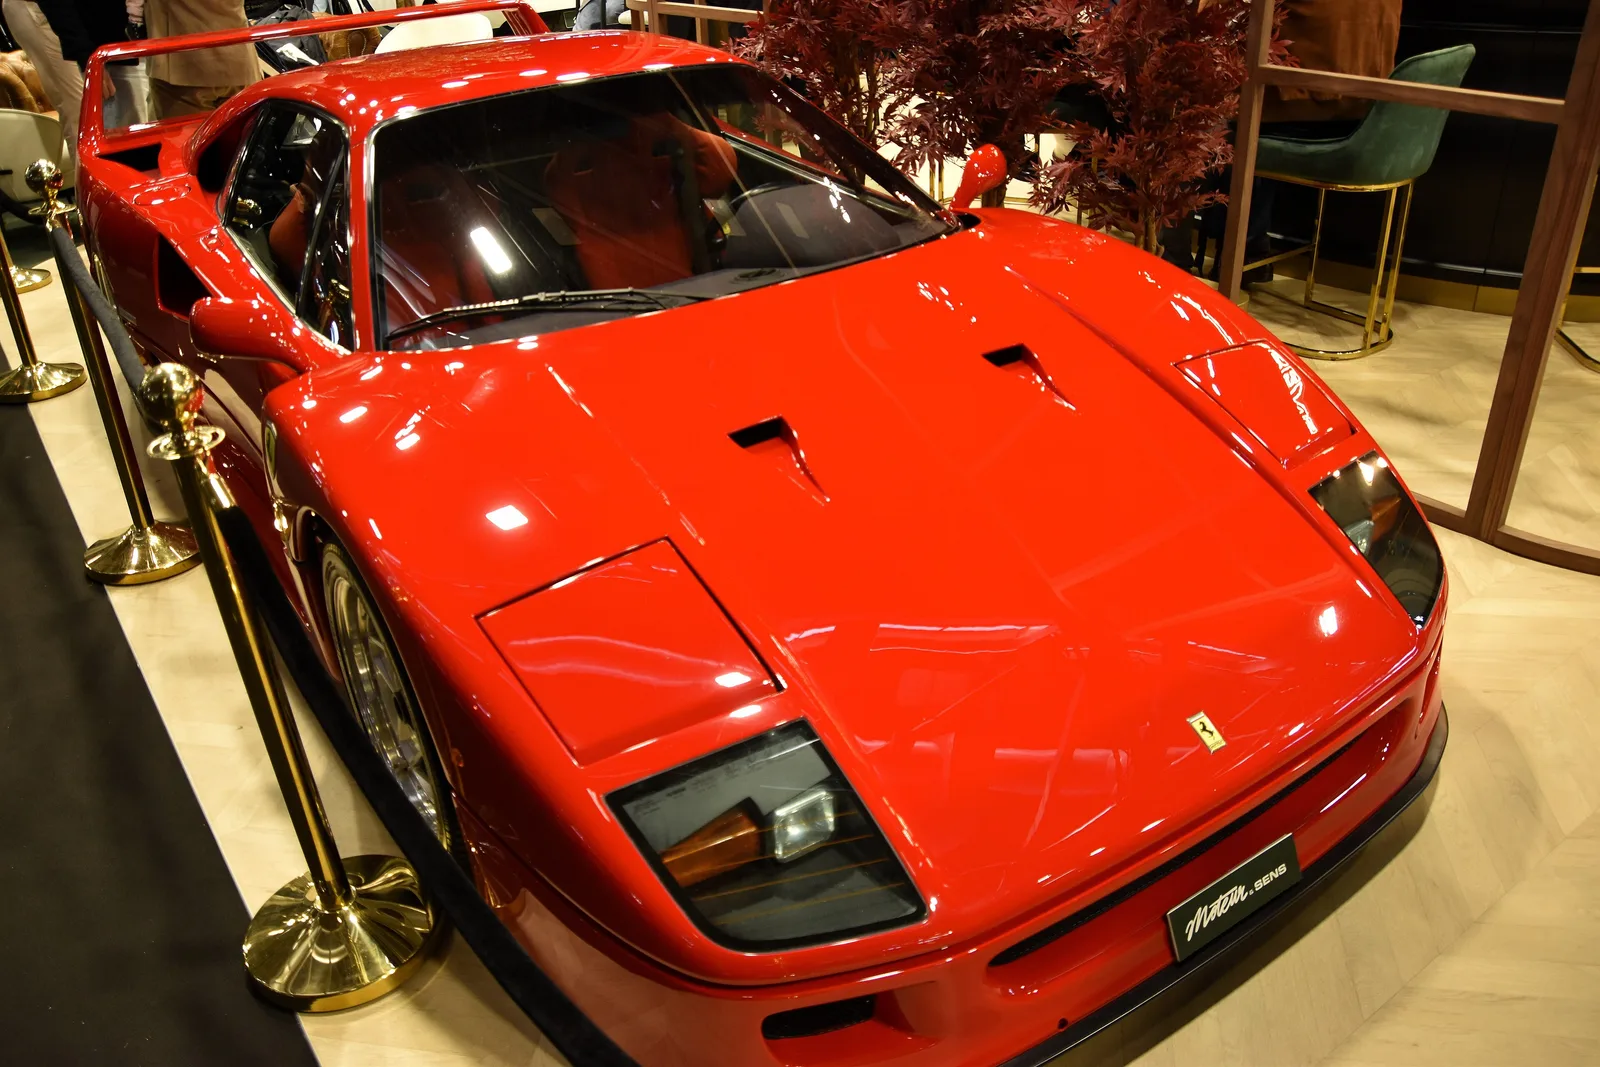
A 1991 Ferrari F40. The car at Monterey was a different example.
What to do with one
A seller should distrust the highest estimate. A high figure can pull bidders up, which is what anchoring means. But at Monterey more than half of the cars sold went below it, and the unsold ones come on top of that. Ask instead which comparable cars the house has sold, for how much and with or without premium. Your own valuation starts from prices like those. The reserve follows from that and not from what someone says on the phone.
A bidder should reverse the order. Find three achieved prices first and write down what you would pay. Only then read the catalogue, because the research suggests the figure sticks once you have seen it. Add the premium too: a $4.5 million hammer, the bottom of that 907's estimate, would have cost close to $5 million at 10%.
And save the estimate if you want to use it later. On the RM Sotheby's page for a 360 Modena from Monterey 2026, all that remains after the sale is $445,000 and the word Sold.
Images: Ferrari Supercars at The Quail (14827322787) by Axion23 (CC BY 2.0); Porsche 907 Langheck (52555634097) by Thomas Vogt from Paderborn, Deutschland (CC BY 2.0); Ferrari F40 (1991) (55081319991) by Charles from Port Chester, New York (CC0). Images resized.


